Understanding Vennlisk’s financial position is essential for the CIMA Strategic Case Study November 2026–February 2027 exam.
The headline numbers initially look encouraging.
Revenue increased.
Operating profit increased.
Profit for the year increased significantly.
But a Strategic Case Study candidate should go further than saying:
“Vennlisk is performing well because profit increased.”
The Board needs to understand why performance has changed, what financial risks remain and what the numbers mean for future strategic decisions.
Let’s break it down.
Join our Free SCS Mini Course:
https://learn.keystoneacademia.com/course/cima-scs-nov-26-mini-course
Register for the free live session:
Keystone Academia – CIMA SCS Registration
Join our CIMA SCS WhatsApp community:
Join the Keystone Academia CIMA SCS WhatsApp Community
Vennlisk Financial Performance at a Glance
| W$ million | 2026 | 2025 | Change |
| Revenue | 12,370.0 | 11,627.8 | +6.4% |
| Gross profit | 1,523.3 | 1,323.4 | +15.1% |
| Operating profit | 1,451.0 | 1,254.7 | +15.6% |
| Finance costs | 436.8 | 436.8 | 0% |
| Profit for year | 770.8 | 621.6 | +24.0% |
The most important observation is that profit is growing substantially faster than revenue.
Revenue grew by approximately 6.4%, while operating profit grew by approximately 15.6% and profit for the year increased by approximately 24.0%.
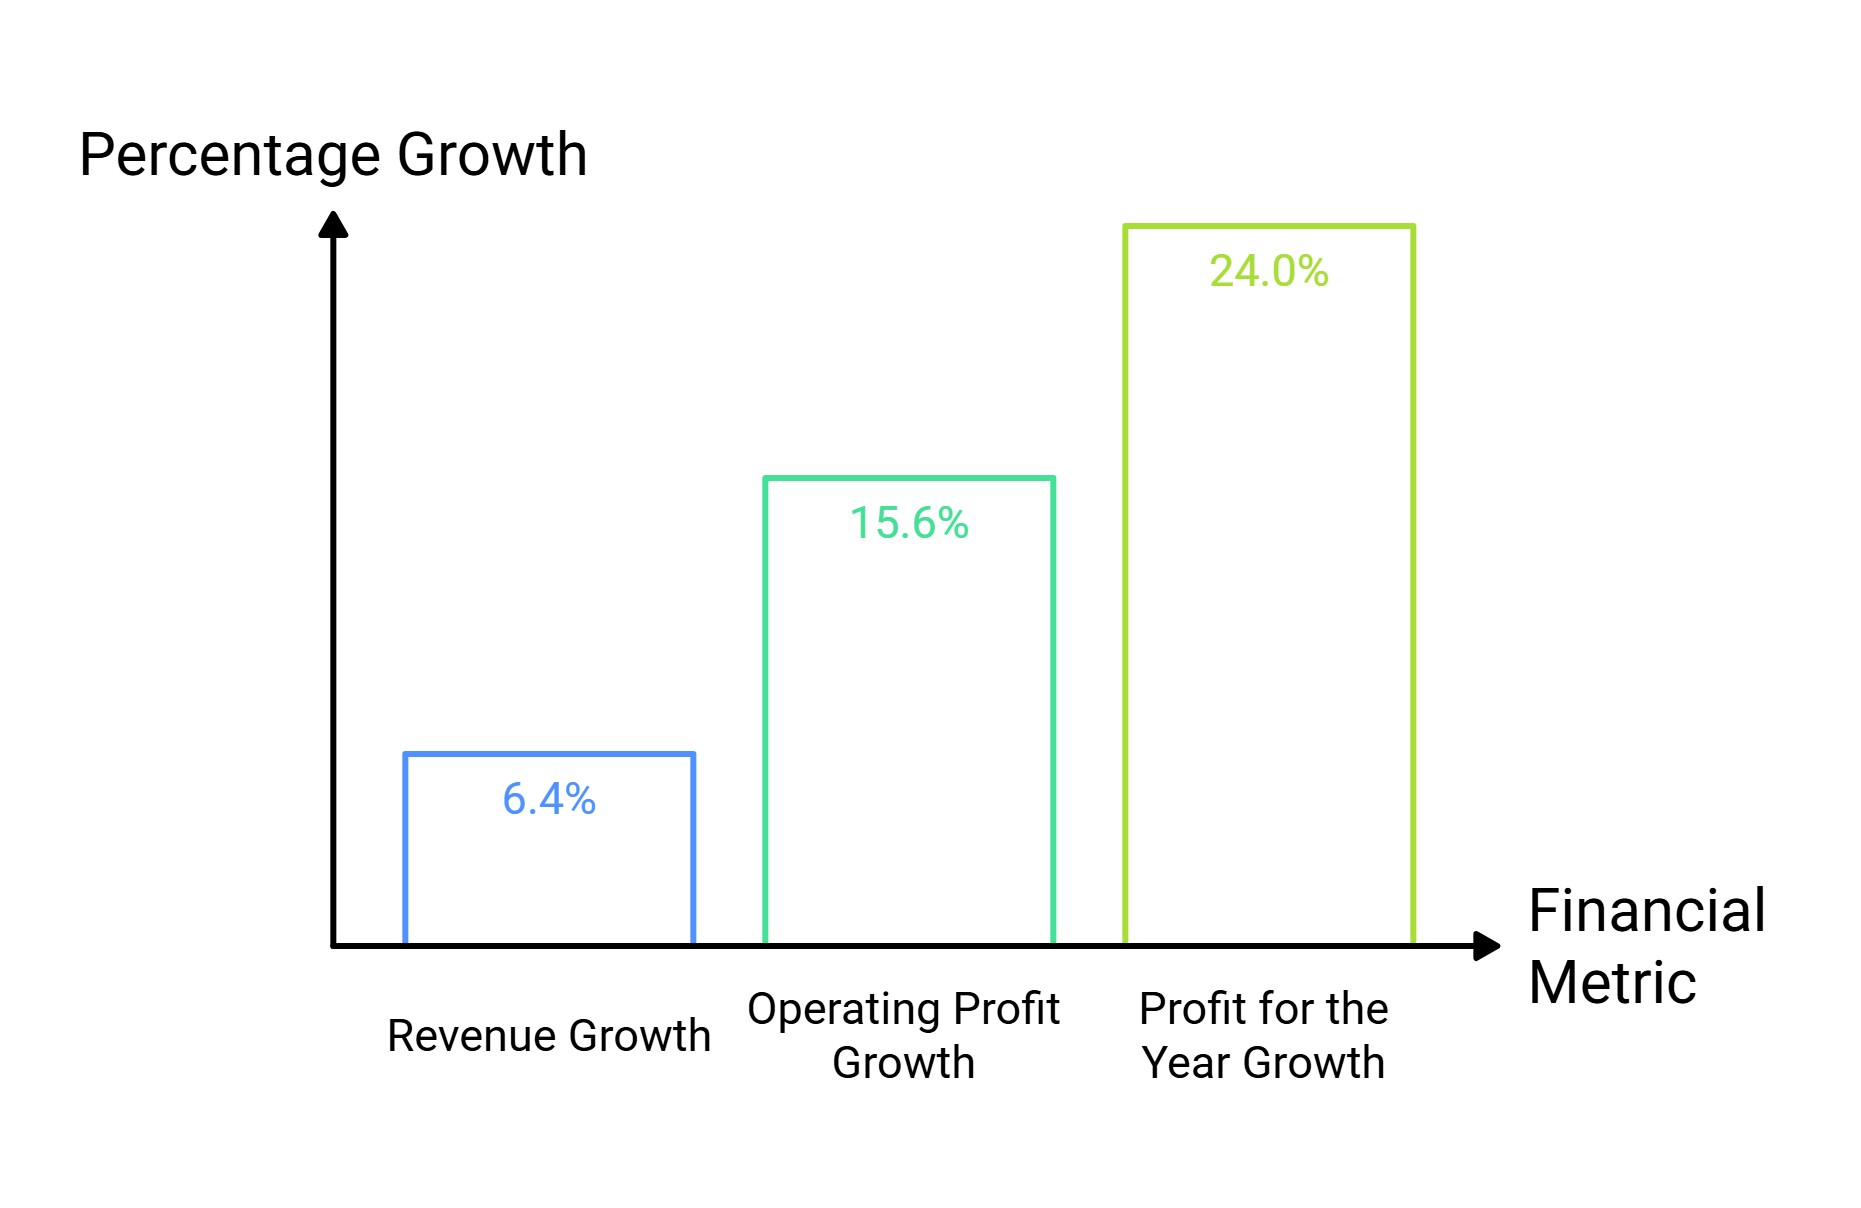
That suggests an improvement in profitability rather than growth being driven simply by higher sales.
1. Revenue Growth Is Positive — But Don’t Stop There
Vennlisk’s revenue increased from W$11,627.8 million to W$12,370.0 million.
That is approximately:
6.4% revenue growth
This is encouraging because it suggests Vennlisk expanded its overall business during the year.
However, revenue growth alone does not tell us whether Vennlisk is creating value.
The Board should ask:
Where did the additional revenue come from?
Was it generated from existing clients or new contracts?
What margins are being earned on those contracts?
Did additional revenue require substantial extra capacity or investment?
The pre-seen financial statements do not provide all this detail.
Therefore, these are questions candidates should raise rather than assumptions they should make.
2. Vennlisk’s Gross Margin Has Improved
Vennlisk’s gross profit increased from W$1,323.4 million to W$1,523.3 million.
Approximate gross profit margins are:
2025: 11.4%
2026: 12.3%
This improvement matters.
Vennlisk generated more gross profit from each W$ of revenue in 2026 than in 2025.
ANALYSIS
Possible explanations could include:
- improved pricing,
- better capacity utilisation,
- greater efficiency,
- changes in the contract mix,
- or improved cost control.
However, the pre-seen does not tell us precisely what caused the improvement.
In the SCS, avoid inventing explanations.
Instead say:
The improvement should be investigated to determine whether it is sustainable.
That demonstrates professional scepticism.
3. Operating Profitability Has Also Improved
Operating profit increased from W$1,254.7 million in 2025 to W$1,451.0 million in 2026.
Approximate operating profit margins are:
| 2025 | 2026 | |
| Operating margin | 10.8% | 11.7% |
This is a positive movement.
Why does this matter?
Vennlisk operates in a labour-intensive industry and faces competition from overseas call centres that can access significantly cheaper labour.
Improving operating profitability may therefore provide Vennlisk with more financial capacity to invest in areas such as:
- employee training
- technology
- AI
- service quality
and potentially:
future growth.
However, management should not improve margins by making cost reductions that damage the quality-based competitive strategy.
4. Profit for the Year Increased by Around 24%
Profit increased from W$621.6 million to W$770.8 million.
That’s approximately:
24.0% growth
The approximate net profit margin increased from:
5.3% in 2025 to 6.2% in 2026.
This is a significant improvement.
But there is an important issue between operating profit and bottom-line profit:
Finance costs.
5. Vennlisk Has Significant Finance Costs
Vennlisk incurred finance costs of:
W$436.8 million
in both 2025 and 2026.
This is substantial compared with operating profit of W$1,451.0 million.
Approximate interest cover improved from:
2.9 times in 2025
to
3.3 times in 2026.
ANALYSIS
The improvement is positive because operating profit has increased while finance costs remained unchanged.
However, W$436.8 million is still a significant annual financial commitment.
This could become particularly important if the Board considers:
- a major acquisition
- AI investment
- new call centres
- or another debt-funded strategic project.
The Board should consider whether taking on additional borrowing would reduce Vennlisk’s financial flexibility.
6. Vennlisk Has W$5.46 Billion of Borrowings
Non-current borrowings are:
W$5,460.0 million
This amount was unchanged between 2025 and 2026.
Vennlisk’s equity at 30 September 2026 was:
W$8,253.1 million
Using debt as a proportion of debt plus equity gives an approximate gearing level of:
39.8%
Alternatively, debt/equity is approximately 66.2%.
The important thing in the exam is not simply producing the percentage.
Business implication
Significant borrowing means strategic decisions involving further debt should be evaluated carefully.
Additional borrowing could:
- increase finance costs,
- increase financial risk,
- reduce financial flexibility,
- and potentially affect shareholder returns.
At the same time, debt is not automatically bad.
If borrowed funds generate returns exceeding their cost and risk remains manageable, debt can support shareholder value.
That is the type of balanced judgement expected at SCS level.
7. Vennlisk Has Significant Goodwill and Intangible Assets
Vennlisk’s 2026 statement of financial position contains:
Goodwill: W$6,274.0 million
Other intangible assets: W$2,249.0 million
Together, these total:
W$8,523.0 million
This is a substantial proportion of Vennlisk’s total assets of W$14,343.8 million.
Why is this important?
Vennlisk has historically grown through both organic growth and acquisitions.
Large goodwill balances can therefore be particularly relevant when analysing previous acquisitions.
If the businesses associated with goodwill fail to generate the expected economic benefits, impairment could become an issue.
This does not mean Vennlisk currently needs to impair its goodwill.
The pre-seen does not state that.
But it is an important area to understand if an unseen introduces:
- an acquisition
- poor performance
- a major client loss
or
- a decline in future cash-flow expectations.
8. What About Vennlisk’s Liquidity?
At 30 September 2026, Vennlisk had:
Trade receivables: W$1,437.3 million
Bank: W$986.1 million
Current liabilities: W$630.7 million
This produces an approximate current ratio of:
3.8 : 1
On the surface, this indicates a substantial level of current assets relative to current liabilities.
Vennlisk also holds almost W$1 billion in bank balances.
ANALYSIS
That could provide useful short-term financial flexibility.
However, liquidity should not be analysed using one ratio alone.
- The Board should consider:
- cash-flow forecasts,
- timing of client receipts,
- future investment commitments,
- debt obligations,
- dividends,
- and unexpected operational requirements.
9. Trade Receivables Are Worth Monitoring
Trade receivables increased from:
W$1,365.4 million
to
W$1,437.3 million.
That is an increase of approximately 5.3%, slightly below the 6.4% increase in revenue.
ANALYSIS
This does not immediately suggest a major deterioration in receivables management.
But receivables remain financially significant.
Vennlisk should maintain effective credit control because delays in collecting client payments could affect cash available for:
- investment,
- debt servicing,
- dividends,
- and normal operations.
10. Vennlisk Paid a Significant Dividend
Vennlisk paid dividends of:
W$509.6 million
during 2026.
Profit for the year was W$770.8 million.
That represents an approximate dividend payout of:
66% of profit
The remaining profit increased retained earnings.
Strategic tension
This creates an important Board decision:
Return cash to shareholders or retain more funds for investment?
Vennlisk may potentially need funds for:
- AI,
- technology,
- employee development,
- acquisitions,
- or other strategic initiatives.
But shareholders may also expect attractive returns.
The Board therefore needs to balance:
dividends today
against
investment for future value creation.
11. What Does This Mean for Shareholder Value?
Vennlisk is a quoted company.
Therefore, financial strategy should ultimately be considered in terms of long-term shareholder value.
Improving profitability could support investor confidence.
But shareholders will also care about:
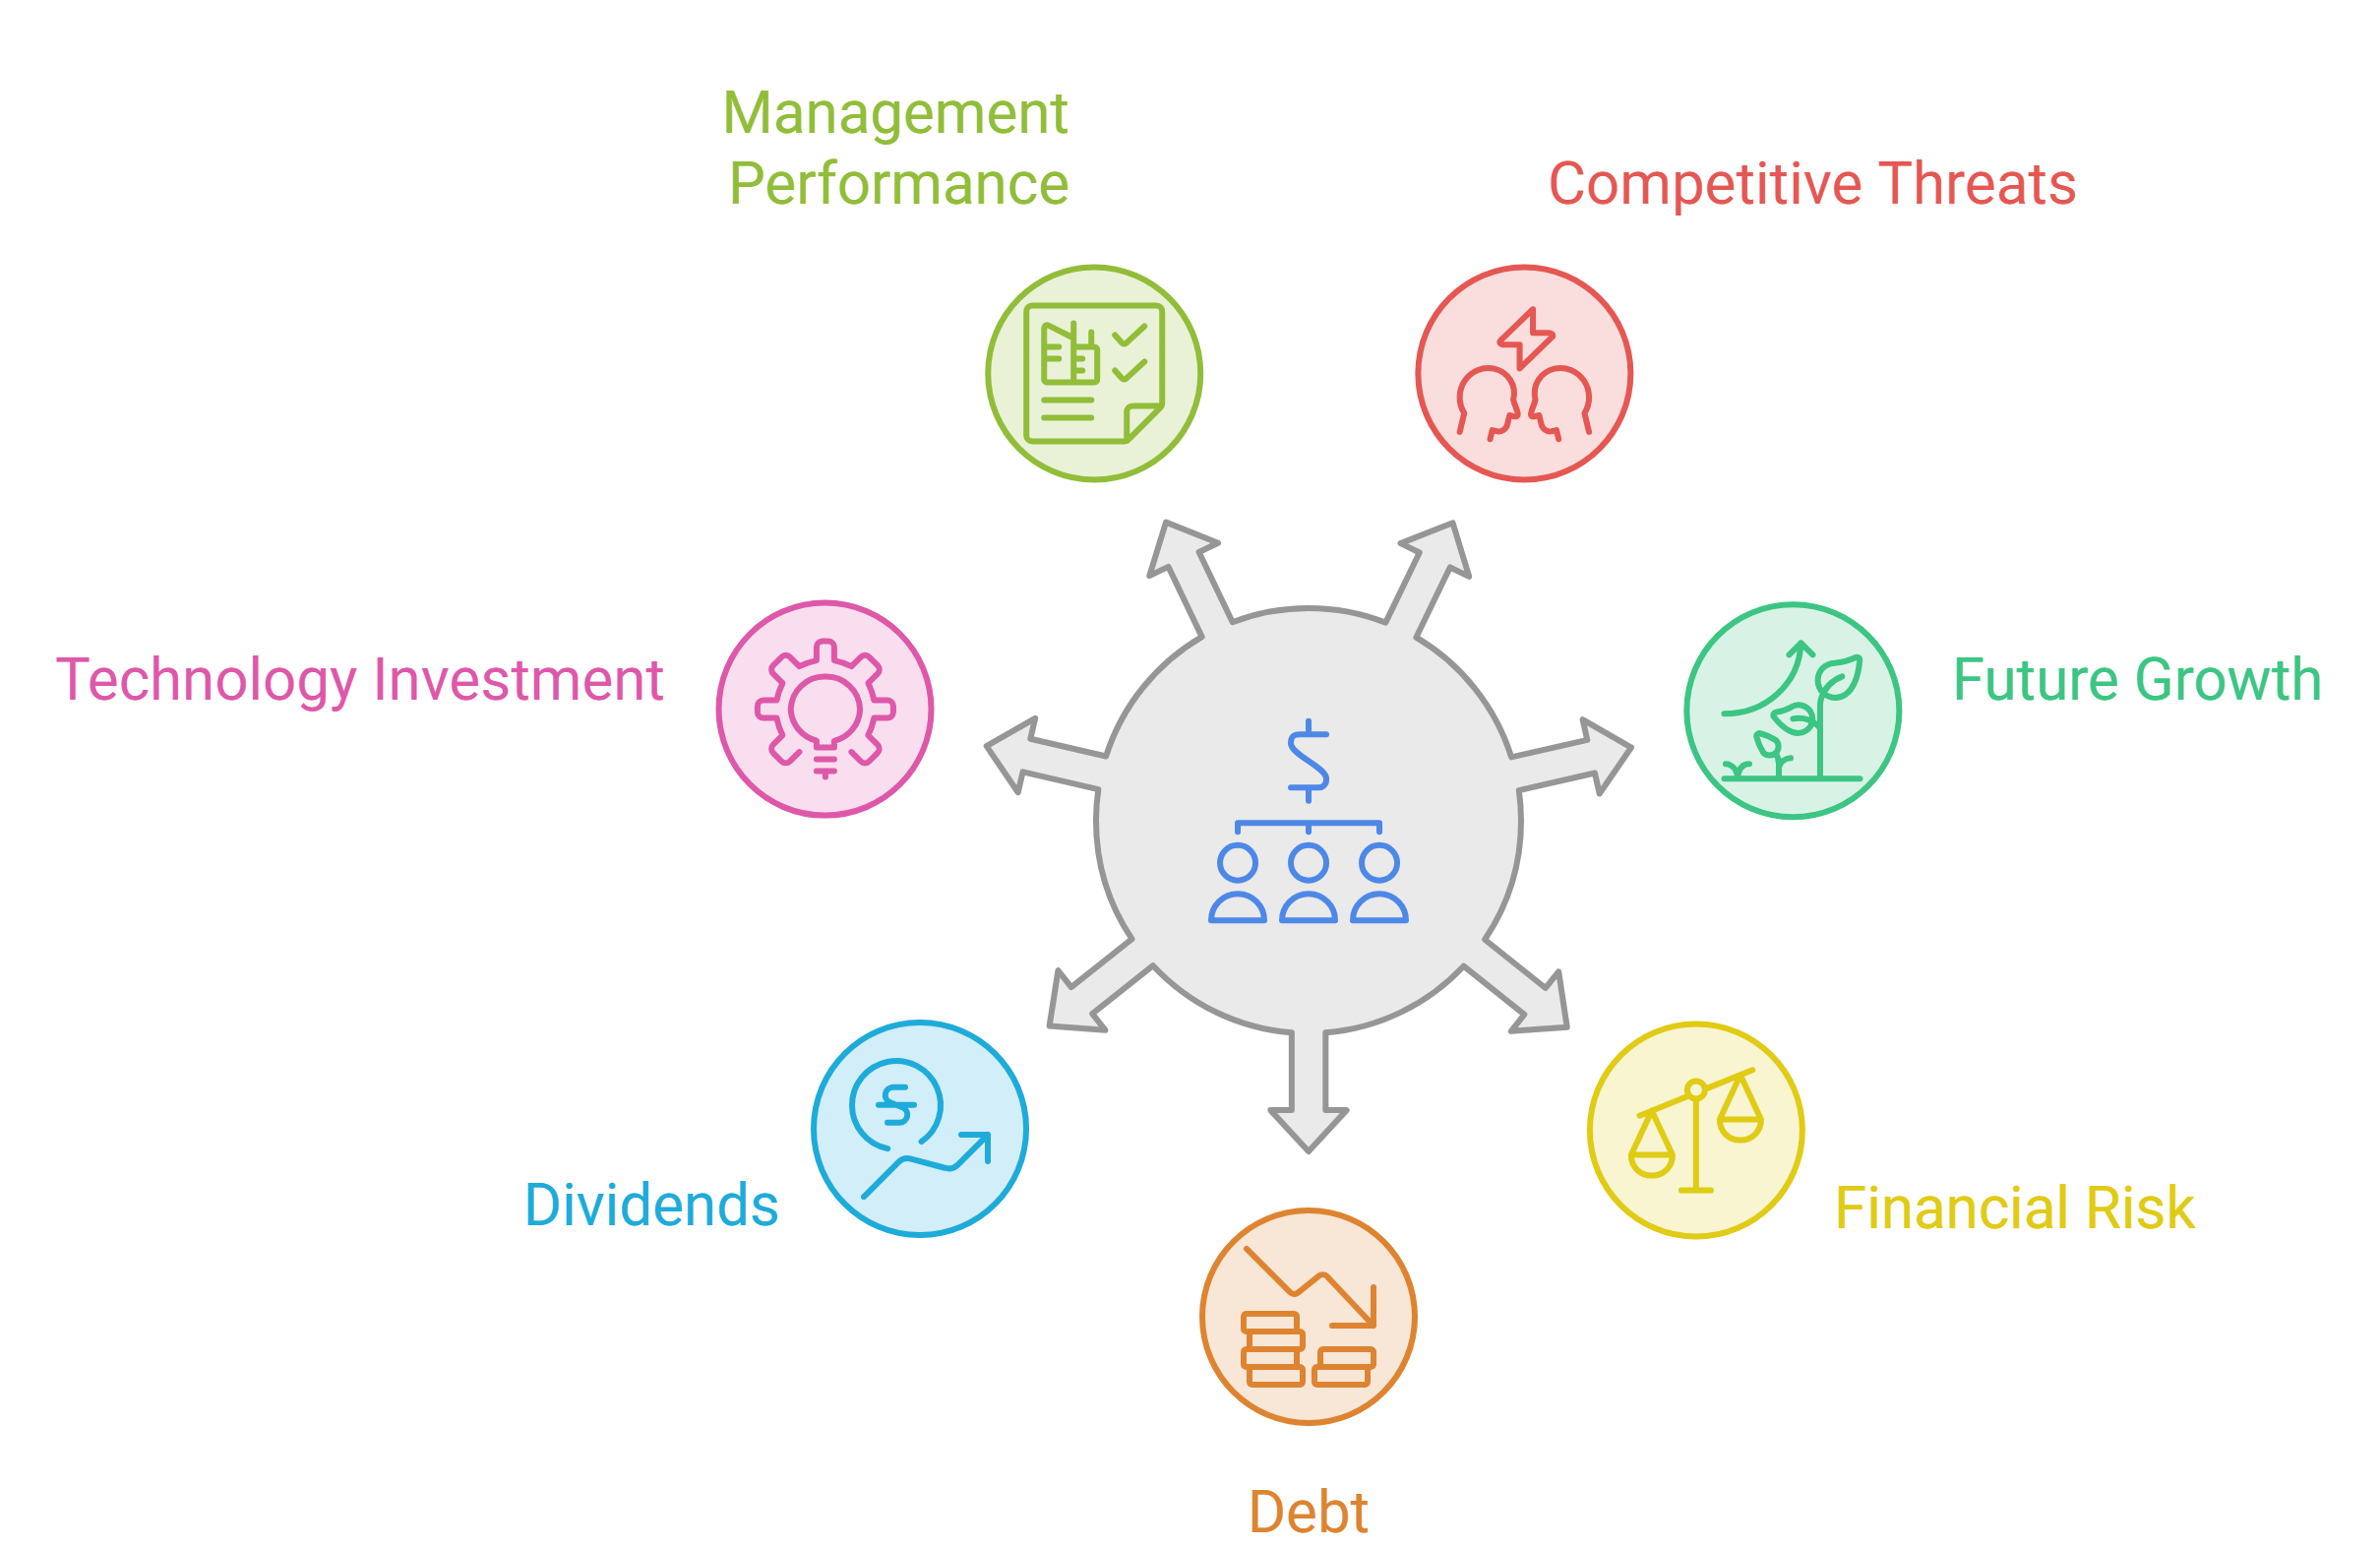
A profitable year does not eliminate strategic risk.
The Most Important Financial Tensions
For exam preparation, remember these relationships:
Profitability vs Service Quality
Cost reduction could increase margins but damage Vennlisk’s quality advantage if taken too far.
Debt vs Growth
Borrowing can finance investment but increases financial risk.
Dividends vs Reinvestment
Cash returned to shareholders cannot simultaneously be invested in AI, acquisitions or other growth opportunities.
Acquisitions vs Financial Risk
Acquisitions could generate growth but could also increase debt and goodwill.
Technology Investment vs Short-Term Profit
AI may require significant upfront investment before benefits are realised.
These are far more valuable than simply memorising ratios.
Vennlisk Financial Dashboard
| Indicator | 2025 | 2026 | Interpretation |
| Revenue | W$11,627.8m | W$12,370.0m | ↑ Positive growth |
| Gross margin | 11.4% | 12.3% | ↑ Improved |
| Operating margin | 10.8% | 11.7% | ↑ Improved |
| Net margin | 5.3% | 6.2% | ↑ Improved |
| Interest cover | 2.9x | 3.3x | ↑ Improved |
| Borrowings | W$5,460m | W$5,460m | Unchanged |
| Bank | W$997.3m | W$986.1m | Slight ↓ |
| Equity | W$7,991.9m | W$8,253.1m | ↑ Increased |
| Dividend | — | W$509.6m | Significant distribution |
What Could the SCS Unseen Introduce?
Financial information could become important if Vennlisk is considering:
- a major AI investment
- an acquisition
- new borrowing
- an equity issue
- a dividend decision
- a major new contract
- an overseas expansion
or
- a significant technology project.
These are plausible developments for practice, not exam predictions.
In each case, candidates should ask:
Can Vennlisk afford it, how should it be financed, what return could it generate and what risks would it create?
How to Write Financial Analysis in the SCS
Avoid:
“Revenue increased by 6.4%, which is good.”
Instead:
Revenue increased by approximately 6.4%, while operating profit increased by approximately 15.6%, indicating an improvement in operating profitability. This could provide Vennlisk with greater capacity to invest in technology or employee development. However, the Board should establish whether the margin improvement is sustainable, particularly given competitive pressure from lower-cost overseas call centres.
That gives you:
Calculation → Interpretation → Vennlisk implication → Board judgement.
That’s the approach students should practise.
Final Takeaway
Vennlisk’s 2026 financial performance shows several positive developments.
Revenue has increased.
Margins have improved.
Operating profit has grown.
Profit for the year has increased substantially.
Interest cover has also improved.
But students should not stop there.
Vennlisk still has:
W$5.46 billion of borrowings
significant finance costs
and
more than W$8.5 billion of goodwill and other intangible assets.
The Board therefore needs to balance:
Growth + Profitability + Investment + Debt + Dividends + Risk
That balance could become highly important if the unseen introduces a major strategic investment or financing decision.
FAQs
Is Vennlisk profitable?
Yes. Vennlisk reported profit for the year of W$770.8 million in 2026, up from W$621.6 million in 2025.
How much did Vennlisk’s revenue grow?
Revenue increased by approximately 6.4%, from W$11,627.8 million to W$12,370.0 million.
Has Vennlisk’s profitability improved?
Yes. Approximate operating margin increased from 10.8% to 11.7%, while net profit margin increased from approximately 5.3% to 6.2%.
How much debt does Vennlisk have?
Vennlisk reported W$5,460.0 million of non-current borrowings at 30 September 2026.
Why is Vennlisk’s goodwill important?
Vennlisk reports W$6,274.0 million of goodwill. Given its history of acquisitions, students should understand the potential implications of goodwill and impairment if future performance deteriorates.
Why is Vennlisk’s dividend relevant?
Vennlisk distributed W$509.6 million in dividends during 2026. This creates a strategic question around how much profit should be distributed versus retained for future investment.
Join our Free SCS Mini Course:
https://learn.keystoneacademia.com/course/cima-scs-nov-26-mini-course
Register for the free live session:
Keystone Academia – CIMA SCS Registration
Join our CIMA SCS WhatsApp community:
Join the Keystone Academia CIMA SCS WhatsApp Community
Next: How Does Vennlisk Compare With Ringcoll?
Financial analysis becomes even more useful when Vennlisk is compared with its closest competitor.
In the next Keystone Academia article, we’ll examine:
Vennlisk vs Ringcoll: Financial & Competitor Analysis for CIMA SCS
We’ll compare profitability, margins, debt, finance costs and financial position — and, more importantly, explain what the differences mean for Vennlisk’s Board and SCS candidates.