Preparing for the CIMA Management Case Study (MCS) exam can be challenging, especially when you understand the technical concepts but struggle to apply them to the business scenario.
For the November 2026 and February 2027 sittings, the pre-seen company is Wuudbreak, an activity holiday park operator.
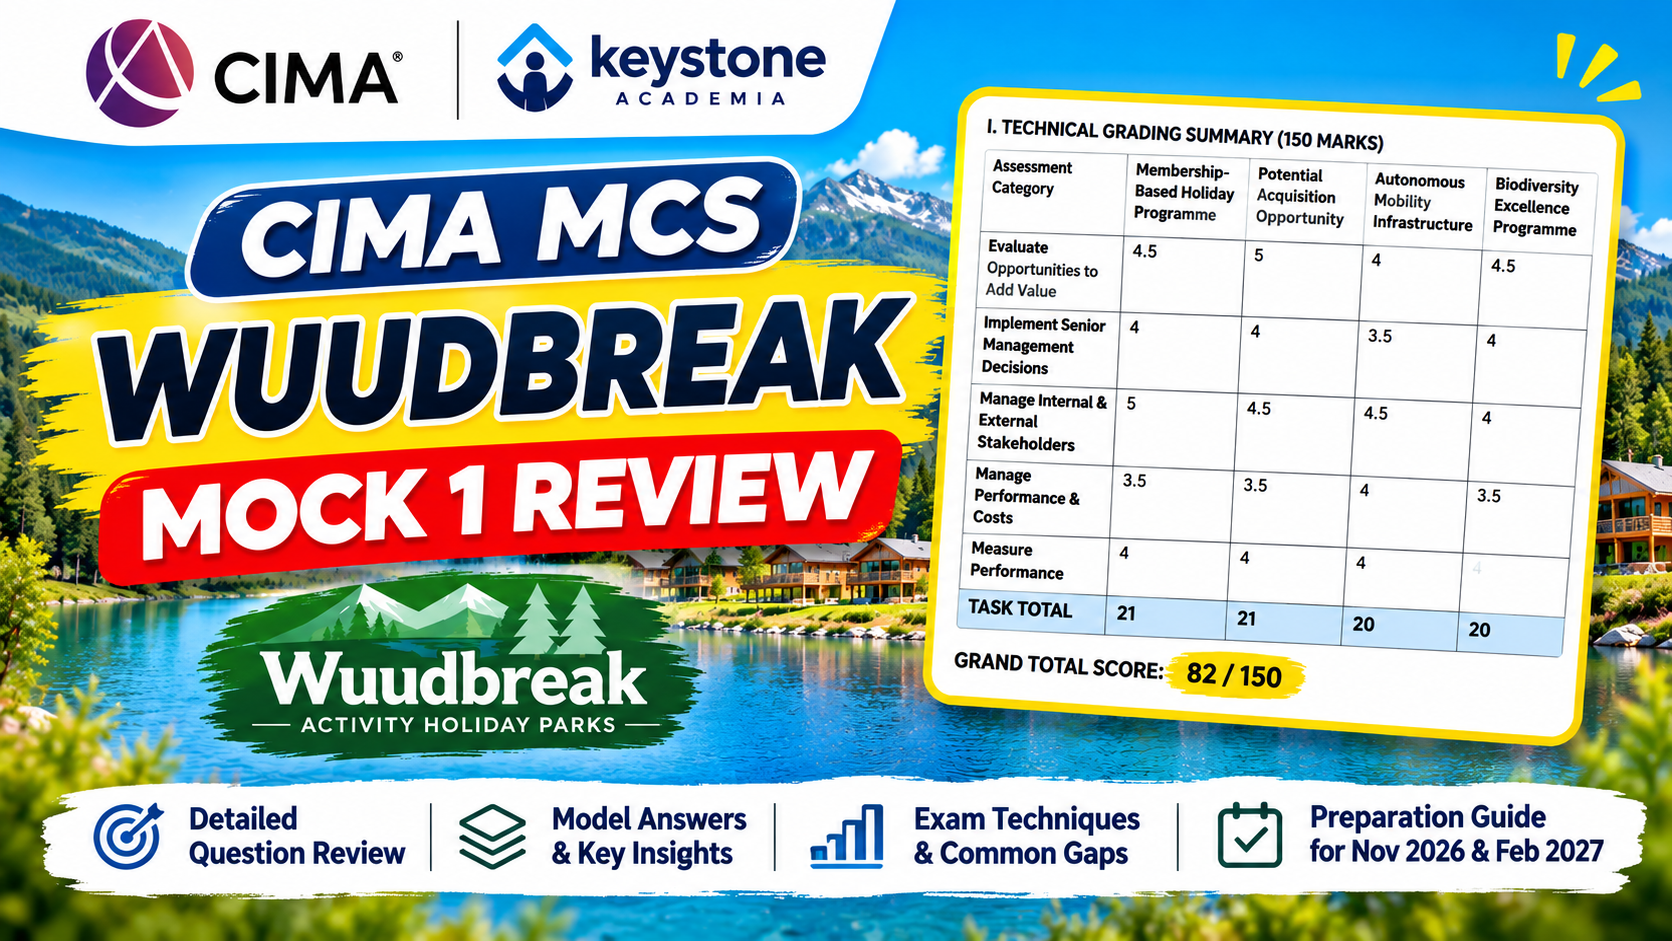
At Keystone Academia, our Wuudbreak Mock 1 is designed to help students practise business decision-making, financial analysis, accounting treatments and performance management under timed exam conditions.
This article reviews the four tasks covered in Mock 1, explains the main technical areas, examines common answer-writing weaknesses identified through mock feedback and provides practical recommendations to improve exam performance.
The scenarios discussed are part of Keystone Academia practice material. They are not predictions of actual CIMA examination questions.
What Does CIMA MCS Wuudbreak Mock 1 Cover?
The mock includes four business scenarios, each requiring students to respond as a Finance Manager.
| Task | Business scenario | Main technical areas |
|---|---|---|
| 1 | Membership-Based Holiday Programme | Customer loyalty, revenue recognition, IFRS 15 |
| 2 | Potential Acquisition Opportunity | Strategic acquisitions, business valuation, debt and equity financing |
| 3 | Autonomous Mobility Infrastructure | Investment appraisal, NPV, IAS 16, financial performance |
| 4 | Biodiversity Excellence Programme | Balanced Scorecard, sustainability KPIs, competitor benchmarking |
The mock is designed for three hours, with four sections of 45 minutes each.
Each section has two requirements with different percentage weightings. Students must allocate their time according to the marks available and address every requirement.
The most important lesson is that technical knowledge alone is not enough.
A strong CIMA MCS answer must explain how the technical issue affects Wuudbreak and what management should do.
Free CIMA MCS Resources for November 2026 and February 2027
Keystone Academia provides several resources to support CIMA Management Case Study preparation.
1. Free CIMA MCS Guidance Sessions
Register for our free CIMA MCS November 2026 and February 2027 guidance sessions.
These sessions are designed to support students with case study preparation, technical revision and exam strategy.
2. Free CIMA MCS Mock Exam
Practise under timed conditions with our free CIMA case study mock exam.
The mock platform is designed to help students experience a three-hour exam-style assessment.
https://mocks.keystoneacademia.com/free-trial
3. Free CIMA MCS Mini Course
Access our free CIMA MCS mini course for additional preparation support.
https://learn.keystoneacademia.com/course/cimamcsminicourse
4. Free CIMA MCS WhatsApp Community
Join other MCS students for preparation updates, study discussions and exam-related support.
https://chat.whatsapp.com/GiFJUGbQRNADkEeQ544hx5
5. CIMA MCS Preparation and Support
Explore Keystone Academia CIMA MCS preparation resources, guidance sessions and tuition support.
Task 1: Wuudbreak Membership Programme and IFRS 15 Revenue Recognition
What is the scenario?
Wuudbreak currently sells holiday breaks on a pay-per-visit basis.
Management is considering an annual membership programme costing N$10,000.
Members would receive benefits such as:
- Priority booking
- Discounts on activities
- Food discounts
- Complimentary short-break stays
The business already has an average occupancy rate of 94%, while 71% of guests are repeat visitors.
Management expects the programme to improve customer retention, encourage additional spending and increase occupancy during quieter periods.
However, there is also concern that discounted membership bookings could replace more profitable full-price bookings.
Requirement A: Evaluate the membership programme and recommend whether Wuudbreak should introduce it
This requirement carries 55% of the task.
Students should consider both the commercial benefits and the potential disadvantages.
1. Customer loyalty and retention
A membership programme could encourage customers to return more frequently.
This may strengthen long-term customer relationships and increase customer lifetime value.
However, Wuudbreak already has strong customer loyalty, with 71% repeat visitors.
Therefore, management must consider whether the programme would attract additional visits or simply offer discounts to customers who would have returned anyway.
Exam application: The important issue is incremental customer value, not simply an increase in membership numbers.
2. Recurring revenue and cash flow
Collecting membership fees at the beginning of the year could provide predictable cash inflows.
This may support working capital management and financial planning.
However, upfront cash collection does not automatically mean that the entire membership fee becomes revenue immediately.
Students should distinguish between cash flow and reported profit.
3. Improving off-peak occupancy
Wuudbreak already operates at approximately 94% occupancy.
This suggests that there may be limited spare capacity during busy periods.
A membership programme could be more beneficial if it encourages customers to visit during quieter periods.
For example, management could offer selected benefits during midweek or off-peak periods rather than providing unrestricted complimentary stays.
This would help utilise spare capacity without unnecessarily replacing full-price bookings.
4. Risk of revenue dilution
A major risk is that existing customers may use discounted membership benefits instead of paying full prices.
This could reduce average revenue per booking.
Management should therefore monitor:
- Incremental revenue generated by members
- Additional spending on food and activities
- Discounts provided
- Complimentary stays used
- Membership administration costs
- Overall contribution and profitability
Recommended conclusion
A controlled pilot programme may be more appropriate than an immediate full rollout.
Wuudbreak could test the scheme during quieter periods, monitor incremental profitability and adjust the membership benefits before expanding it.
The recommendation should be supported by financial and operational evidence.
Requirement B: Explain the IFRS 15 revenue recognition treatment
This requirement carries 45%.
It tests whether students can apply IFRS 15 Revenue from Contracts with Customers to the membership programme.
Can Wuudbreak recognise the full N$10,000 immediately?
Generally, no.
Receiving the membership fee does not automatically mean that all the promised services have been delivered.
Under IFRS 15, revenue is recognised when or as the relevant performance obligations are satisfied.
Management should identify the promised benefits and determine whether they represent distinct performance obligations or a combined service.
The transaction price must then be allocated appropriately.
What happens when the customer pays?
Wuudbreak receives cash, but any amount relating to services not yet delivered is initially recognised as a contract liability.
As the company provides the membership benefits, the relevant revenue is recognised.
Example
Assume, for illustration, that the full N$10,000 membership fee relates to a single stand-ready service delivered evenly over 12 months.
Monthly revenue would be approximately:
N$10,000 ÷ 12 = N$833.33
This is only a simplified example. The actual accounting depends on the contractual benefits, whether separate performance obligations exist and how those obligations are satisfied.
What about unused membership benefits?
Some customers may not use all their benefits.
This is commonly referred to as breakage.
Under IFRS 15, expected breakage may be recognised in proportion to the pattern of rights exercised when the company expects to be entitled to that amount.
Where a reliable estimate is not available, recognition is generally deferred until the likelihood of the customer exercising the remaining rights becomes remote, subject to the relevant requirements.
Financial reporting implications
Students should explain the impact on:
- Cash balances
- Contract liabilities
- Revenue recognition
- Reported profitability
- Future performance obligations
Common answer-writing mistake: Explaining the five-step IFRS 15 model without applying it to the specific membership benefits and financial reporting consequences.
Task 2: Wuudbreak Acquisition Strategy and Financing Decisions
What is the scenario?
Wuudbreak is considering acquiring a smaller regional resort operator.
The target operates three forest-based resorts in neighbouring regions and has developed a reputation for eco-tourism experiences.
The acquisition would increase Wuudbreak accommodation capacity by approximately 25%.
The estimated purchase price is N$750 million.
Management believes the acquisition could generate purchasing efficiencies, geographical expansion and cross-selling opportunities.
However, the company must also consider integration difficulties and financing risks.
Requirement A: Should Wuudbreak proceed with the acquisition?
This requirement carries 50%.
Strategic fit
The acquisition could support the long-term growth strategy by increasing capacity and expanding into neighbouring regions.
The target also has experience in eco-tourism, which could complement the existing Wuudbreak business model.
However, management should establish whether the acquisition offers advantages that could not be achieved through organic expansion.
Operating synergies
Combining operations could create opportunities for:
- Bulk purchasing discounts
- Shared administration
- Cross-selling
- Improved supplier negotiations
- Wider geographical coverage
Students should not assume that these benefits will automatically materialise.
Management should estimate the value of the expected savings and the costs required to achieve them.
Integration risks
Acquisitions can create difficulties when combining employees, systems and operating procedures.
Potential problems include:
- Different management cultures
- Incompatible IT systems
- Employee resistance
- Unexpected integration expenditure
- Disruption to customer service
Wuudbreak should develop a clear post-acquisition integration plan.
Shareholder value and investment appraisal
The purchase price of N$750 million is a significant financial commitment.
Students should explain that growth alone does not guarantee shareholder value creation.
Management should assess the expected future cash flows, integration costs, acquisition price and required rate of return.
Net Present Value (NPV) analysis can help determine whether the expected benefits justify the investment.
Sensitivity analysis can also show how changes in assumptions could affect the decision.
Recommended conclusion
Wuudbreak should proceed only if satisfactory due diligence and financial appraisal demonstrate that the acquisition is expected to create value.
The recommendation should not be based solely on the increase in accommodation capacity.
Requirement B: Should Wuudbreak use debt or equity financing?
This requirement carries 50%.
Three main financing options are considered.
Option 1: Debt financing
Additional borrowing would allow existing shareholders to retain their ownership percentages.
Interest may also provide a tax advantage, depending on the applicable tax rules.
However, debt creates interest and repayment obligations.
Wuudbreak must consider the impact on gearing, interest cover, cash flow and financial flexibility.
Option 2: Equity financing
Issuing shares could strengthen the capital base without creating mandatory interest payments.
This may reduce financial pressure during the acquisition and integration process.
However, issuing new shares can dilute existing shareholder ownership and may increase the overall cost of capital.
Option 3: Combined debt and equity financing
A combination of debt and equity could balance financial risk and shareholder dilution.
The appropriate structure should depend on:
- Existing gearing
- Interest cover
- Forecast operating cash flows
- Cost of debt and equity
- Integration expenditure
- Financial flexibility
- Shareholder expectations
Recommended conclusion
A mixed financing structure may be appropriate, subject to detailed financial assessment.
Students should explain why the selected structure supports Wuudbreak financial stability and long-term shareholder value.
Common answer-writing mistake: Listing generic advantages and disadvantages of debt and equity without discussing the N$750 million acquisition, existing borrowing levels and expected cash flows.
Task 3: Autonomous Mobility Infrastructure, NPV and IAS 16
What is the scenario?
Wuudbreak is considering investing N$180 million in autonomous mobility infrastructure.
The proposal includes:
- Autonomous shuttle hubs
- Charging facilities
- Digital guidance systems
Management expects the investment to improve accessibility, attract more visitors and support future growth.
Forecasts indicate positive cash inflows over a ten-year period.
However, the financial benefits depend on customer adoption of autonomous transport.
Requirement A: Evaluate the investment proposal
This requirement carries 60%.
Strategic benefits
The investment could improve accessibility to parks located far from major transport links.
This may attract customers who currently find those locations difficult to reach.
It could also strengthen the reputation of Wuudbreak as an innovative holiday park operator.
However, students must consider whether the technology creates a sustainable competitive advantage.
Investment appraisal using NPV
The Board should evaluate whether the expected future cash flows justify the initial N$180 million investment.
NPV considers the time value of money and the required rate of return.
A positive NPV indicates that the project is expected to create value based on the assumptions used.
However, a positive forecast alone is not sufficient when the underlying assumptions are highly uncertain.
Sensitivity analysis
Wuudbreak should assess how the project outcome could change if:
- Visitor growth is lower than expected
- Customer adoption is slower
- Maintenance costs increase
- Technology upgrades become more expensive
- Additional customer spending is below forecast
Scenario analysis could compare optimistic, realistic and pessimistic outcomes.
Capacity constraints
Wuudbreak already has high occupancy.
Therefore, attracting more visitors may not always produce significant additional accommodation revenue.
Management should consider whether the investment would instead increase off-peak demand, improve customer spending or enhance accessibility.
Recommended conclusion
The project has potential strategic benefits, but management should not commit to the investment without a robust financial appraisal.
A detailed NPV assessment, sensitivity analysis and realistic customer adoption forecasts would support the decision.
Requirement B: Explain the IAS 16 accounting treatment
This requirement carries 40%.
The accounting treatment is based on IAS 16 Property, Plant and Equipment.
Should the N$180 million be capitalised?
Qualifying expenditure on physical infrastructure should generally be capitalised when the relevant recognition criteria are met.
This could include shuttle hubs, charging facilities and eligible installation costs.
The assets should initially be measured at cost, including directly attributable expenditure necessary to bring them into the location and condition required for intended use.
Digital systems may require separate assessment to determine whether IAS 16 or another accounting standard applies.
Depreciation
Qualifying depreciable assets should be depreciated over their estimated useful lives once available for use.
This means the investment may increase non-current assets initially, while depreciation charges affect future reported profits.
Maintenance and upgrades
Routine maintenance is generally recognised as an expense.
However, qualifying subsequent expenditure that enhances or replaces components may be capitalised when the relevant recognition criteria are satisfied.
Impairment risk
If customer adoption is lower than expected, the project may not generate the anticipated financial benefits.
This could create an impairment indicator under IAS 36.
Management should monitor the performance of the investment and assess whether impairment testing is required.
Financial performance implications
Students should explain the difference between:
Cash flow: The project requires significant upfront expenditure.
Profit: Qualifying expenditure is capitalised, with depreciation affecting future periods.
Statement of financial position: Non-current assets increase when qualifying infrastructure is recognised.
Investment returns: Management must assess whether the assets generate sufficient value relative to the capital invested.
Common answer-writing mistake: Focusing entirely on the commercial benefits of the investment and leaving the accounting treatment unanswered.
Even when students are unsure of the complete technical answer, they should attempt every requirement and explain the relevant principles.
Task 4: Biodiversity Performance, Balanced Scorecard and Competitor Analysis
What is the scenario?
Wuudbreak is considering expanding its Biodiversity Excellence Programme.
The programme includes:
- Increasing protected wildlife areas
- Restoring habitats
- Monitoring biodiversity
- Strengthening environmental performance
Management believes the programme could improve the reputation of Wuudbreak and support long-term growth.
Competitors have already published detailed biodiversity targets and sustainability performance indicators.
Requirement A: How should Wuudbreak measure the success of the programme?
This requirement carries 50%.
The model solution recommends using a Balanced Scorecard supported by biodiversity-specific performance indicators.
This approach considers financial and non-financial outcomes.
1. Financial perspective
Wuudbreak should assess whether biodiversity initiatives contribute to sustainable financial performance.
Possible measures include:
- Revenue growth
- Operating profit margin
- Return on capital employed
- Revenue from biodiversity-related activities
- Return on biodiversity investment
Environmental initiatives should be evaluated for both their environmental outcomes and their financial implications.
2. Customer perspective
Biodiversity is an important part of the nature-based holiday experience.
Possible measures include:
- Repeat visitor percentage
- Customer satisfaction
- Wildlife experience satisfaction
- Participation in nature-based activities
- Net Promoter Score
Wuudbreak already reports strong customer loyalty and satisfaction.
Management should assess whether biodiversity improvements strengthen these outcomes.
3. Internal process perspective
Management should measure how effectively biodiversity activities are delivered.
Possible indicators include:
- Habitat restoration projects completed
- Percentage of biodiversity targets achieved
- Environmental incidents
- Wildlife monitoring activities
- Compliance with conservation procedures
4. Learning and growth perspective
Employees play an important role in environmental performance.
Possible measures include:
- Environmental training hours
- Employee qualifications
- Employee engagement
- Sustainability training completion
- Employee suggestions implemented
5. Biodiversity-specific KPIs
The programme should also monitor actual environmental outcomes.
Examples include:
- Species count
- Wildlife population trends
- Area of protected habitats
- Habitat restoration progress
- Ecosystem diversity
- Number of endangered species recorded
Leading and lagging indicators
Students should distinguish between activities that may influence future performance and the results achieved.
Leading indicators may include staff training, habitat restoration activities and biodiversity monitoring.
Lagging indicators may include changes in species diversity, customer satisfaction and profitability.
Using both types of indicators provides a more complete picture.
Requirement B: Assess Wuudbreak performance against competitors
This requirement carries 50%.
The model solution compares Wuudbreak with Vannpark.
| Measure | Wuudbreak | Vannpark |
|---|---|---|
| Revenue | N$843.7m | N$776.2m |
| Operating profit | N$367.9m | N$501.4m |
| Operating profit margin | 43.6% | 64.6% |
| Number of parks | 9 | 11 |
What does the comparison show?
Wuudbreak generates more revenue despite operating fewer parks.
This suggests strong revenue generation from its premium nature-based holiday offering.
However, its operating profit margin is substantially lower than that of Vannpark.
This raises questions about operating efficiency and cost management.
Students should avoid concluding that higher revenue automatically means stronger overall financial performance.
Customer performance
Wuudbreak also reports:
- 71% repeat visitors
- 96% positive guest satisfaction ratings
- 94% occupancy
These indicators suggest strong customer loyalty and demand.
However, management must continue improving the customer experience while controlling costs.
Biodiversity reporting
Competitors have developed more detailed biodiversity targets and public sustainability disclosures.
Wuudbreak should consider introducing:
- Measurable species diversity targets
- Habitat restoration targets
- Wildlife population monitoring
- Ecosystem diversity indicators
- Clear reporting timelines
This would improve accountability and allow more meaningful performance comparisons.
Recommended conclusion
Wuudbreak should continue using its nature-based offering as a competitive strength while improving operational efficiency and biodiversity reporting.
The most useful recommendations should include specific performance measures, targets and monitoring responsibilities.
What Did the Anonymised Mock 1 Review Reveal?
A review of an anonymised student submission identified several important learning points.
The student demonstrated an understanding of the business scenarios and was able to identify relevant strategic, operational and financial considerations.
However, the feedback highlighted areas where the answers could be strengthened.
These observations relate to one reviewed submission and should not be interpreted as evidence that all MCS students make the same mistakes.
1. Good points need stronger financial support
In the membership programme and acquisition questions, the student identified relevant advantages and risks.
However, the feedback recommended more detailed consideration of financial projections, profitability, cost savings and financial metrics.
Lesson: Do not stop after identifying a benefit. Explain its potential financial impact and what management should measure.
2. Recommendations need to be more specific
The student often provided sensible recommendations, including pilot testing and further financial evaluation.
However, some recommendations needed clearer conditions, financial measures and implementation details.
Lesson: Explain what management should do, why it should do it and what evidence is required before proceeding.
3. Technical accounting requirements must not be overlooked
The autonomous mobility task included a requirement about infrastructure expenditure and future financial performance.
This part was not attempted in the reviewed submission.
Lesson: Students should manage their time carefully and attempt all requirements. Leaving a requirement unanswered removes the opportunity to demonstrate knowledge in that area.
4. Performance measures need targets and timelines
The biodiversity response identified useful environmental, customer and employee indicators.
However, the feedback recommended clearer targets, timelines and connections to financial performance.
Lesson: A list of KPIs is not enough. Explain how management would use those measures to evaluate success and take corrective action.
5. Benchmarking should lead to practical action
The student recognised that competitors had stronger biodiversity reporting.
The feedback suggested providing more specific recommendations for addressing these differences.
Lesson: Competitor analysis should identify performance gaps and recommend actions to close them.
How to Write Better CIMA MCS Answers
A practical approach is to follow four steps.
Step 1: Identify the requirement
Look carefully at the instruction.
Common words include:
- Evaluate
- Assess
- Advise
- Recommend
- Discuss
These words indicate the type of response required.
For example, an evaluation normally requires consideration of relevant benefits, disadvantages and implications, leading to a supported judgement.
Step 2: Identify the relevant scenario information
Use the figures and facts provided.
For Wuudbreak, this might include:
- 94% occupancy
- 71% repeat visitors
- N$750 million acquisition price
- N$180 million infrastructure investment
- Financial performance compared with competitors
These details help make an answer specific to the company.
Step 3: Explain the business impact
Avoid simply describing a theory.
For example:
Basic answer:
Debt financing increases financial risk.
Improved answer:
Financing the N$750 million acquisition entirely through borrowing could increase Wuudbreak gearing and interest obligations. This may reduce financial flexibility during the integration period, particularly if expected acquisition synergies take longer to achieve.
The second answer is stronger because it connects the technical issue to the business decision.
Step 4: Make a justified recommendation
Recommendations should follow logically from the analysis.
For example:
Wuudbreak should consider a combination of debt and equity financing, subject to projected gearing, interest cover and cash flow analysis. This could reduce excessive borrowing risk while limiting shareholder dilution.
A strong recommendation should be realistic and supported by the scenario.
CIMA MCS Time Management: How to Use the Three Hours Effectively
The mock provides three hours across four sections.
Each section lasts 45 minutes.
Students must divide their time between the requirements according to the percentages shown.
| Task | Requirement A | Requirement B |
|---|---|---|
| 1 | 55% | 45% |
| 2 | 50% | 50% |
| 3 | 60% | 40% |
| 4 | 50% | 50% |
For Task 3, for example, the suggested allocation is:
- Requirement A: 27 minutes
- Requirement B: 18 minutes
These figures represent the full section time, including reading and planning. Students should reserve a small portion of each allocation for understanding the requirement and organising their answer.
The key lesson is to avoid spending so much time on the first requirement that the second is left unanswered.
How to review a completed mock exam
After attempting a mock, students should not simply read the model answer and move on.
A more useful review process is:
- Read the original requirement again.
- Compare your response with the model solution.
- Identify relevant points you included.
- Identify missing business implications or financial analysis.
- Review the feedback on your recommendation.
- Rewrite one or two weaker sections.
- Practise another question under timed conditions.
The objective is to improve answer quality, not memorise the model solution.
CIMA MCS Wuudbreak Mock 1: Frequently Asked Questions
What topics are covered in the Wuudbreak Mock 1?
The mock covers a membership programme, a potential acquisition, autonomous mobility infrastructure and biodiversity performance management. Technical areas include IFRS 15, investment appraisal, debt and equity financing, IAS 16, the Balanced Scorecard and competitor benchmarking.
How can I improve my CIMA MCS answer-writing technique?
Start by identifying the requirement, selecting relevant scenario information, explaining the business implications and making a justified recommendation. Avoid writing generic textbook explanations without applying them to Wuudbreak.
How should I prepare for CIMA MCS November 2026?
Focus on understanding the Wuudbreak pre-seen, revising relevant E2, P2 and F2 concepts, practising timed questions and reviewing feedback carefully. Use your remaining preparation time to address recurring weaknesses rather than attempting to memorise every possible scenario.
Is IFRS 15 important for CIMA MCS Wuudbreak?
IFRS 15 is relevant to the membership programme scenario in Keystone Academia Mock 1. Students should understand performance obligations, contract liabilities, revenue recognition and the financial reporting impact of advance payments.
This does not mean IFRS 15 is guaranteed to appear in the actual examination.
How do I evaluate an acquisition in the CIMA MCS exam?
Consider strategic fit, expected synergies, integration risks, investment appraisal, financial implications and shareholder value. Recommendations should be supported by relevant business and financial evidence.
What is the difference between NPV and accounting profit?
NPV evaluates discounted future cash flows to assess investment value. Accounting profit follows the relevant financial reporting rules and may include non-cash expenses such as depreciation. Both provide useful information, but they answer different questions.
How does IAS 16 apply to the autonomous mobility investment?
Qualifying physical infrastructure costs may be capitalised as property, plant and equipment. Depreciation is then recognised over the estimated useful life, while impairment and subsequent expenditure must be assessed under the applicable accounting requirements.
Why is the Balanced Scorecard relevant to Wuudbreak?
The Balanced Scorecard helps management evaluate financial performance alongside customer outcomes, internal processes, and learning and growth. Biodiversity-specific KPIs can be added to assess environmental outcomes more directly.
How many mock exams should I practise before CIMA MCS?
There is no single number that guarantees success. The quality of practice and feedback is more important than simply completing a large number of mocks.
Students should aim to improve their ability to interpret questions, apply technical knowledge and produce well-supported answers within the available time.
Are the Wuudbreak Mock 1 scenarios predictions for November 2026 or February 2027?
No. The scenarios are educational practice questions developed to help students apply the relevant syllabus knowledge to Wuudbreak. They should not be treated as confirmed or predicted examination content.
Free CIMA MCS Resources for November 2026 and February 2027
Keystone Academia provides several resources to support CIMA Management Case Study preparation.
1. Free CIMA MCS Guidance Sessions
Register for our free CIMA MCS November 2026 and February 2027 guidance sessions.
These sessions are designed to support students with case study preparation, technical revision and exam strategy.
2. Free CIMA MCS Mock Exam
Practise under timed conditions with our free CIMA case study mock exam.
The mock platform is designed to help students experience a three-hour exam-style assessment.
3. Free CIMA MCS Mini Course
Access our free CIMA MCS mini course for additional preparation support.
4. Free CIMA MCS WhatsApp Community
Join other MCS students for preparation updates, study discussions and exam-related support.
5. CIMA MCS Preparation and Support
Explore Keystone Academia CIMA MCS preparation resources, guidance sessions and tuition support.
Final Thoughts: What Students Should Learn From Wuudbreak Mock 1
The most important lesson from this mock is that a good CIMA MCS answer must combine technical knowledge with business application.
Students should be able to explain:
- Whether a proposal creates value for Wuudbreak
- What financial and operational risks management should consider
- How accounting standards affect financial reporting
- Which performance measures are relevant
- What management should do next and why
Do not focus only on producing an answer that looks similar to the model solution.
Instead, focus on understanding the requirement, using the information provided and making clear, commercially sensible recommendations.
Whether you are preparing for the November 2026 or February 2027 CIMA MCS exam, regular timed practice followed by careful feedback review can help strengthen your exam technique.
Start with a free CIMA MCS mock exam:
https://mocks.keystoneacademia.com/free-trial
Keystone Academia | CIMA Management Case Study Preparation